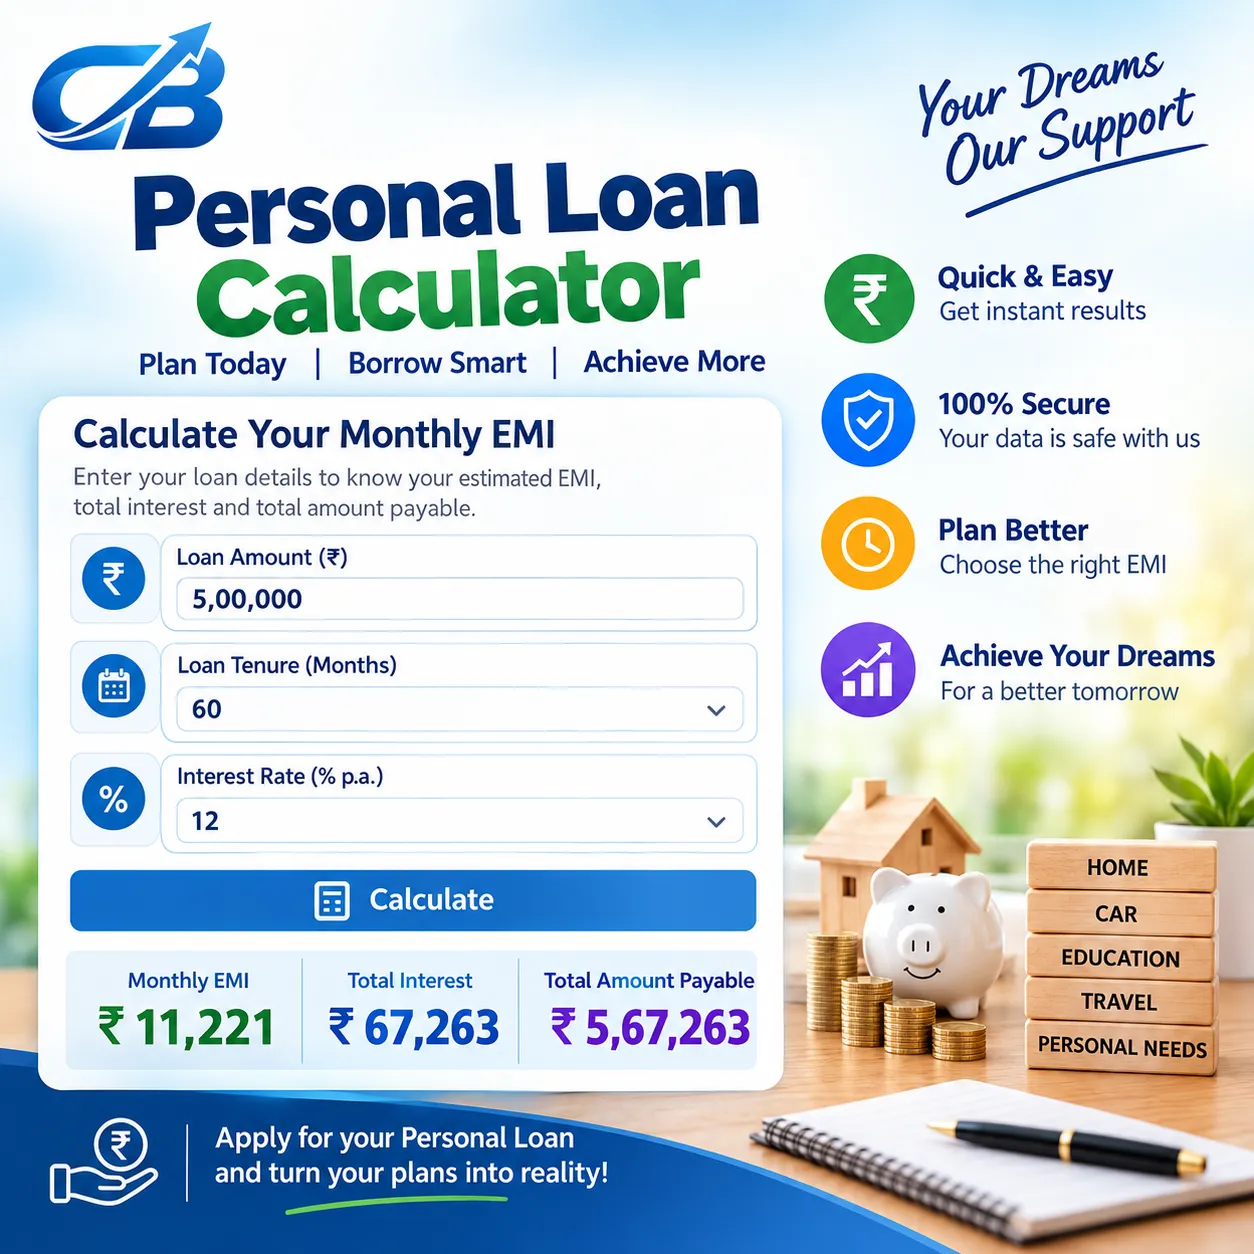

Running the numbers through a calculator before reaching out to lenders provides several practical advantages:
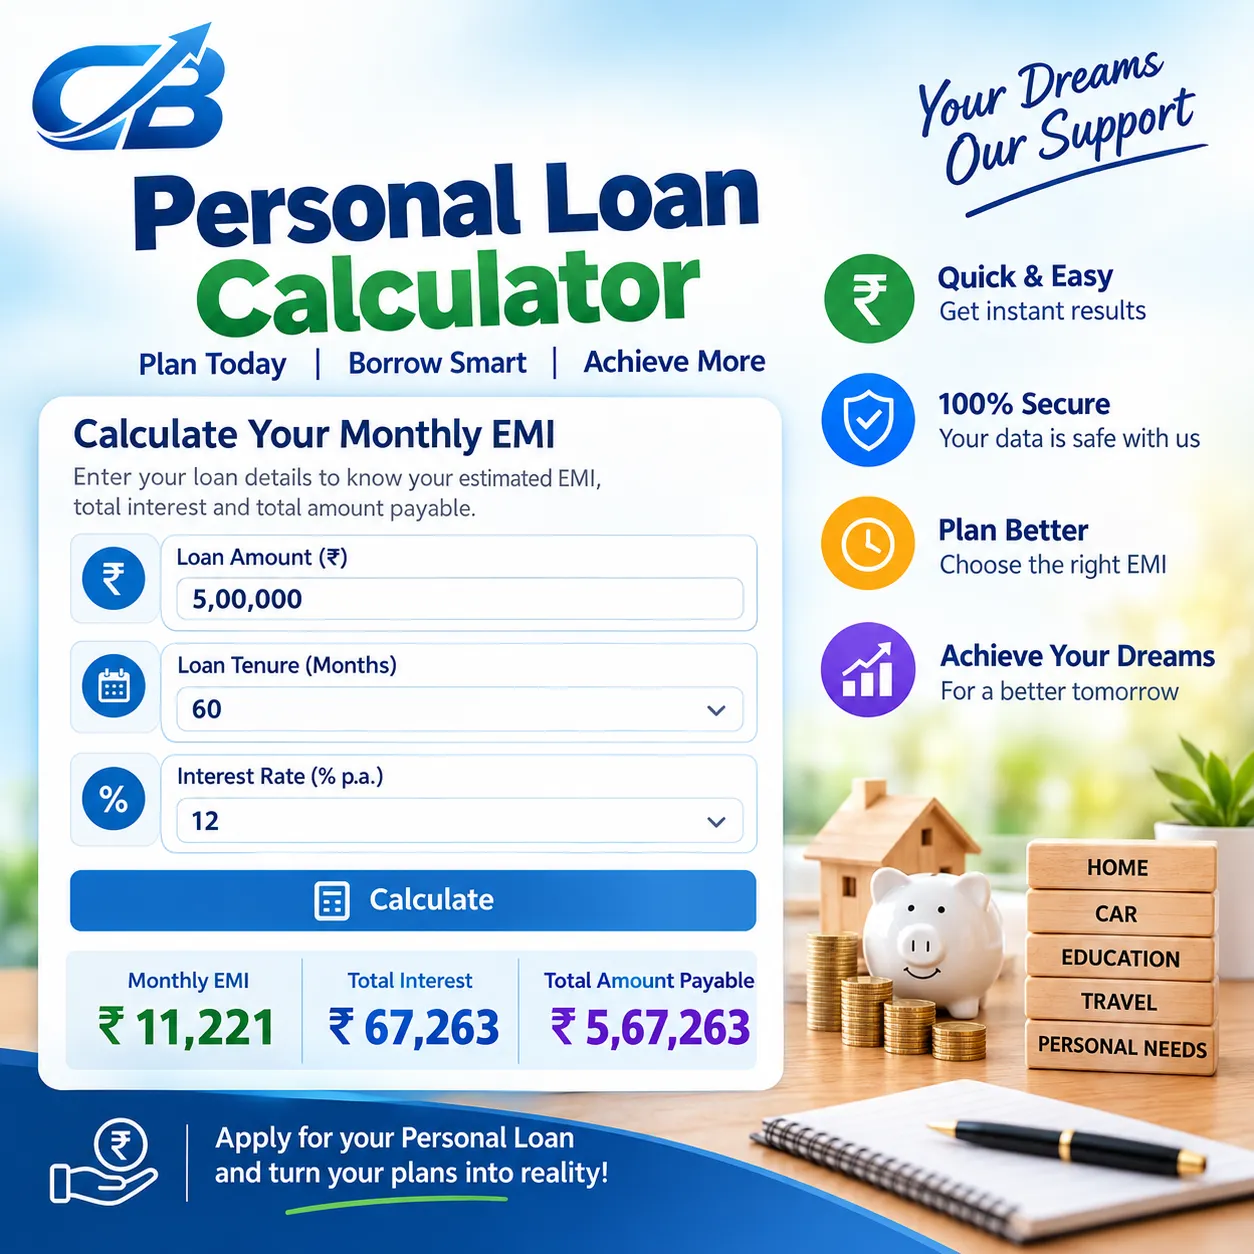
Accurate Household Budgeting: Knowing your EMI will help you make sure your new monthly commitment leaves plenty of space for rent, groceries, utilities and emergency savings.
Finding the Balance Between Tenure and Interest:
Shorter Tenures (12–24 Months): monthly EMIs but you pay much less in total interest over time.
Longer Tenures (36–60 Months): more manageable monthly payments though the overall interest cost will be higher.
Spotting the Flat vs. Reducing Rate Trap: A "flat" interest rate of 10% may sound cheaper than a 13% "reducing‑balance" rate. Flat rates calculate interest on the full original principal for the whole tenure. A calculator that uses reducing‑balance formulas shows the cost of borrowing.
Keeping Your FOIR Within Safe Limits: Most lenders want your Fixed Obligation to Income Ratio (FOIR) to stay below 40% to 50% of your monthly in‑hand income. Calculating your EMI ahead of time ensures your new loan does not push you past this limit.
What Key Figures Should You Look for in the Results? When the calculation appears on your screen review three figures:
Monthly EMI: The exact amount that will be auto‑debited from your bank account every month.
Total Interest Payable: The total additional money paid to the lender across the tenure.
Total Repayment (Principal + Interest): The financial cost of the loan from start, to finish.
What Else Should You Keep in Mind? While the calculator provides an estimate of your interest and EMI remember to account for a few additional one‑time charges:
Processing Fees: Typically 1% to 3% of the loan amount plus 18% GST deducted upfront from the amount you receive.
Prepayment Charges: If you get a bonus and wish to close the loan check whether the lender charges a foreclosure penalty.
Final Thoughts: Taking two minutes to test loan amounts and repayment periods prevents financial strain and helps you choose an offer that matches your repayment capacity.
Before signing a sanction letter or submitting your KYC documents run your numbers on a personal loan calculator to find a tenure and EMI plan that protects your monthly cash flow from day one.












Sign in to leave a comment.