

India's personal loan market has moved from a niche banking product to a mainstream, high-velocity credit segment. The market is estimated at roughly USD 187.4 billion in 2026, and digital-first NBFCs alone have taken their personal loan book to about Rs 1.54 lakh crore as of June 2026 — up 28% year-on-year, according to data compiled by the Fintech Association for Consumer Empowerment (FACE). In the April-June 2026 quarter, digital NBFCs sanctioned roughly 3.4 crore personal loans worth Rs 64,656 crore, a volume that would have been operationally impossible to process manually.
That scale is only possible because the software running underneath personal lending has changed fundamentally. In 2026, personal loan management software is no longer a back-office ledger — it is an AI-assisted, API-connected, compliance-aware system that decides, in real time, who gets a loan, how much, at what price, and how it gets collected. This article looks at the trends reshaping that software, what they mean for lenders, and what to look for when evaluating a platform.
What Is Personal Loan Management Software?
Personal loan management software is an end-to-end digital platform that automates every stage of a personal loan's life — from the moment a borrower applies to the day the loan is closed. It typically spans:
- Loan Origination: digital application intake, document collection and KYC verification
- Credit Underwriting: bureau pulls, income analysis and scorecard-based decisioning
- Sanctioning: offer generation, e-signing and digital loan agreements
- Disbursement: bank account validation and fund transfer via NEFT, IMPS or UPI
- Servicing: repayment schedules, amortization and prepayment handling
- Collections: EMI reminders, delinquency management and settlement workflows
- Reporting & Compliance: regulatory reports, portfolio dashboards and audit trails
In India, this stack must also plug into country-specific infrastructure — Aadhaar-based eKYC, DigiLocker, the Account Aggregator (AA) framework, the four major credit bureaus, NACH mandate registration, and RBI's compliance requirements for digital lenders.
8 Trends Shaping Personal Loan Management Software in 2026
1. Agentic and Multi-Signal AI Underwriting
Underwriting has moved well past a single bureau score. Industry commentary on 2026 digital lending apps points to the rise of “agentic AI” — systems that autonomously pull data from multiple sources, build a composite borrower profile, and calculate a dynamic probability of default in real time, rather than simply flagging an application for manual review. Modern platforms typically pull all four major bureaus (CIBIL, Experian, Equifax, CRIF High Mark) simultaneously and blend that with alternative signals such as GST filings, banking transaction patterns and employment stability indicators.
2. Account Aggregator-Powered Cash-Flow Underwriting
The RBI-backed Account Aggregator framework allows borrowers to consent to share verified financial data — bank statements, GST data and more — directly with a lender's underwriting engine. This is proving especially valuable for new-to-credit (NTC) and self-employed borrowers who may have thin bureau files but a stable, verifiable cash flow. Recent FACE/CRIF data shows sanction value to borrowers with under one year of credit history rose 178% year-on-year, a trend that cash-flow-based underwriting is directly enabling.
3. Instant, Paperless KYC
Aadhaar OTP-based eKYC, DigiLocker document pulls and selfie-based liveness checks have replaced in-branch identity verification for most digital personal loans. This has compressed a process that once took days into a step that completes in minutes, directly enabling same-day approvals for pre-qualified and salaried borrower segments.
4. No-Code Product Configuration
Lenders increasingly expect to launch a new loan variant — a top-up loan, a co-borrower product, a salary-advance offering — without a development sprint. No-code business rule engines let credit and product teams configure eligibility rules, interest structures (flat, reducing, step-up) and approval workflows directly, cutting what used to be a three-to-six-month build cycle down to hours or days.
5. Embedded Finance and Co-Lending at Scale
RBI's co-lending framework, which allows banks and NBFCs to share risk in structures such as a 60:40 split, is helping personal loans reach borrowers beyond traditional bank branch networks. At the same time, embedded finance — loan offers placed inside e-commerce, payroll or other non-financial apps — is becoming a meaningful origination channel, pushing lending software to be API-first so it can plug into partner platforms rather than only a lender's own app.
6. Predictive, Early-Warning Collections
Rather than waiting for a missed EMI, 2026-era platforms increasingly run continuous behavioural monitoring — tracking signals like rising credit utilisation or irregular repayment patterns — to flag accounts at risk of delinquency before they default. Collections teams then get AI-prioritised outreach lists and multi-channel (call, SMS, WhatsApp) automation instead of a flat, unsegmented call list.
7. Compliance Automation Built Into the Workflow
RBI's Digital Lending Guidelines (2022), the Fair Practices Code, and data localisation requirements are no longer handled as a separate legal checklist — they are increasingly built into the loan workflow itself: automatic Key Fact Statement generation, consent logging, tamper-proof audit trails, and auto-generated regulatory reports such as CRILC submissions and NPA provisioning statements. This matters because digital lenders are scaling fast; keeping compliance manual at that scale is a growing operational risk.
8. Risk-Adjusted, Personalised Pricing
Flat, one-size-fits-all interest rates are giving way to dynamic, risk-adjusted pricing, where a borrower's real-time probability-of-default score informs the rate and loan amount they are offered. Combined with faster underwriting, this lets lenders extend credit further down the risk curve — FACE/CRIF data shows borrowers in high and very-high-risk score categories already account for about 29% of digital NBFC sanction value, compared with 9% for banks — while still pricing that risk appropriately, provided the underlying models and monitoring are sound.
How AI Is Changing Each Stage of the Personal Loan Lifecycle
The table below contrasts the traditional, largely manual approach to personal lending with the AI-driven approach typical of a modern 2026 platform.
| Loan Stage | 2020-Era Approach | 2026 AI-Driven Approach |
|---|---|---|
| Application Intake | Paper forms / static web forms | Dynamic, field-level-logic digital forms across web, app & partner channels |
| KYC & Identity | Branch visit, physical documents | Aadhaar eKYC, DigiLocker, selfie liveness checks, instant verification |
| Credit Underwriting | Manual file review, single bureau pull | Multi-bureau pulls + Account Aggregator cash-flow data + AI scorecards in seconds |
| Approval Decision | 2-7 working days | Real-time to same-day for most pre-qualified and salaried segments |
| Disbursement | Cheque / branch-initiated transfer | Instant NEFT/IMPS/UPI payout after e-sign |
| Repayment Collection | Manual follow-up, physical ECS | NACH/UPI Autopay with automated retry logic |
| Risk Monitoring | Monthly or quarterly portfolio review | Continuous, AI-based Early Warning Signals on behavioural data |
| Collections | Generic call lists | AI-prioritised, segmented outreach via call/SMS/WhatsApp |
What to Look for in Personal Loan Management Software in 2026
Given these trends, a few capabilities separate a genuinely modern platform from a relabeled legacy system:
- No-code configuration for loan products, eligibility rules and workflows, so business teams aren't dependent on a development queue.
- Native, pre-built integrations with eKYC, DigiLocker, the Account Aggregator framework and all major credit bureaus.
- An AI-based credit scoring engine that blends bureau and alternative data, with explainable, auditable decisions.
- Automated NACH and UPI Autopay repayment handling, including dishonour and retry logic.
- An early-warning system for proactive, behaviour-based collections rather than reactive recovery.
- Compliance features mapped explicitly to RBI's Digital Lending Guidelines, Fair Practices Code and data localisation norms.
- A pricing model (usage-based vs. large upfront licence) that matches your loan volumes and growth stage.
- A realistic, demonstrable implementation timeline — ask for a live demo of the exact workflow you'd run, not a generic walkthrough.
Where Roopya Fits In
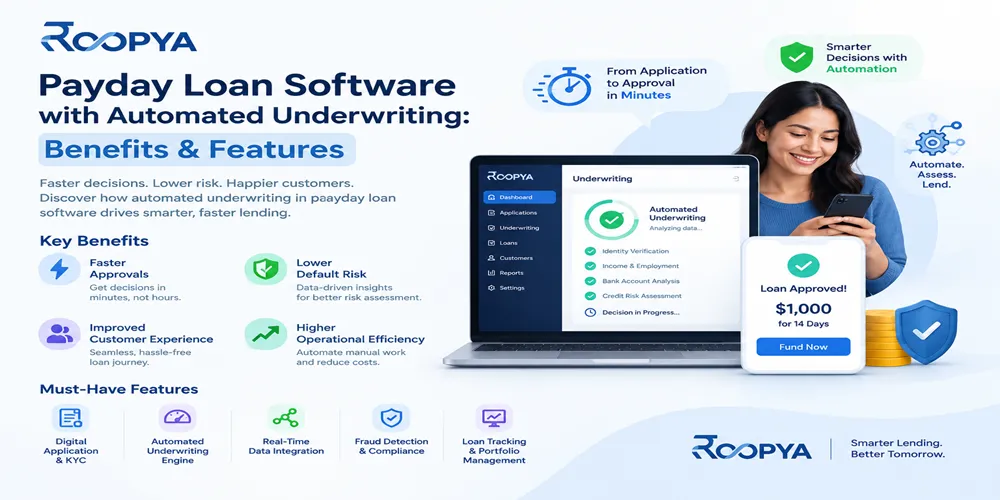
Roopya (roopya.money) is built around exactly this shift. Its Personal Loan Management Software combines loan origination, AI-powered underwriting, disbursement, servicing and collections into a single no-code platform, with over 300 pre-integrated APIs covering credit bureaus, KYC providers (Aadhaar, DigiLocker, PAN), bank-statement analysers via the Account Aggregator ecosystem, fraud-detection engines and payment gateways.
Lenders can configure loan products — including top-up loans, co-borrower loans and salary advance products — without writing code, run multi-bureau pulls alongside custom application, behavioural and collection scorecards, and register e-NACH mandates during origination itself for Day 1 repayment readiness. An Early Warning System flags at-risk accounts based on behavioural signals before they default, and the platform maintains tamper-proof audit trails with auto-generated regulatory reports to support RBI compliance. Roopya reports typical onboarding timelines of around one day for platform access and initial product configuration, with most lenders fully live within one to two weeks, and it operates on a usage-based pricing model with no upfront licensing cost.
Risks and Open Questions to Watch
The shift to AI-driven personal lending is not without risk, and a responsible platform — and a responsible lender — should address these directly rather than treat them as someone else's problem:
- Model risk: An underwriting model is only as good as its training data and ongoing monitoring; lenders should insist on explainability and regular model validation, not a black box.
- Fraud sophistication: As underwriting gets smarter, so do fraud attempts — synthetic identities and document manipulation increasingly require AI-based fraud detection to counter AI-assisted fraud.
- Data privacy: With Account Aggregator and bank-statement data flowing into underwriting, strict consent management, encryption and data localisation are non-negotiable rather than optional add-ons.
- Over-extension risk: Faster, cash-flow-based underwriting is extending credit to thinner-file and higher-risk borrowers; portfolio quality needs continuous monitoring, not just faster approvals.
- Regulatory evolution: RBI's digital lending framework continues to evolve; software that hard-codes today's rules without a path to update them quickly becomes a compliance liability.
Personal loan management software in 2026 looks very different from the systems lenders were running even three or four years ago. AI-driven, multi-signal underwriting, Account Aggregator-based cash-flow data, no-code product configuration, and predictive collections have become baseline expectations rather than differentiators — and the market data backs this up, with digital NBFC personal lending growing 28% year-on-year even as it reaches younger, thinner-file and more geographically dispersed borrowers.
For lenders evaluating a platform, the questions worth asking are less about whether a vendor uses “AI” — most now do — and more about how explainable its decisions are, how deeply it integrates with India's KYC and data infrastructure, how quickly it can go live, and how seriously it takes RBI compliance as the regulatory framework continues to evolve.
If you'd like to see how Roopya's no-code personal loan management platform applies these 2026 trends to a live workflow, you can request a free demo here.
Frequently Asked Questions (FAQ)
What is personal loan management software?
Personal loan management software is a digital platform that automates the full lifecycle of a personal loan — application intake, KYC, credit underwriting, sanctioning, disbursement, repayment servicing and collections — replacing manual processes and disconnected spreadsheets with a single, rule-driven system.
How is AI changing personal loan management software in 2026?
AI is now used across the lifecycle: for credit scoring that blends bureau data with alternative signals such as bank-statement cash flow and employment patterns, for document and identity verification, for fraud detection, and for predicting early signs of delinquency so collections teams can act before an account turns delinquent.
What is the Account Aggregator (AA) framework and why does it matter for personal loans?
The Account Aggregator framework is an RBI-backed, consent-based system that lets borrowers securely share their financial data (bank statements, GST filings, and more) directly with lenders. It gives underwriting engines richer, verified cash-flow data beyond a traditional credit bureau score, which is especially useful for new-to-credit and self-employed borrowers.
Is digital personal loan growth in India backed by real numbers?
Yes. According to the Fintech Association for Consumer Empowerment (FACE), India's digital NBFC personal loan book reached roughly Rs 1.54 lakh crore as of June 2026, up about 28% year-on-year, with digital NBFCs sanctioning around 3.4 crore loans worth Rs 64,656 crore in the April-June 2026 quarter alone.
What should lenders look for when choosing personal loan management software in 2026?
Key criteria include no-code product configuration, native integration with KYC, Account Aggregator and bureau data sources, an AI-based underwriting and fraud-detection engine, automated NACH/UPI Autopay repayment handling, an early-warning collections module, and built-in compliance with RBI's Digital Lending Guidelines and data localisation norms.
How long does it take to implement personal loan management software?
It depends on the platform. No-code, cloud-native platforms can go live in as little as a day for standard loan products and within two to four weeks for more complex configurations such as co-lending, while legacy systems built on custom core-banking extensions often take six to eighteen months to implement.
Is AI-driven personal loan underwriting compliant with RBI regulations?
AI-driven underwriting can be fully compliant when the platform is built around RBI's Digital Lending Guidelines (2022) and Fair Practices Code — meaning transparent disclosure of terms via a Key Fact Statement, a human-reviewable decision trail, data localisation, and no coercive recovery practices. Lenders should confirm these safeguards directly with any software vendor.
What is the difference between a Loan Origination System (LOS) and a Loan Management System (LMS) for personal loans?
A Loan Origination System (LOS) manages everything before disbursement — the application, KYC, credit decisioning and sanctioning — while a Loan Management System (LMS) manages everything after disbursement, including amortization schedules, EMI collection, prepayments and closure. Modern platforms like Roopya combine both into a single system.
Can small or new NBFCs afford modern personal loan management software?
Yes. Many 2026-era platforms, including Roopya, use a pay-as-you-use pricing model based on loan volume rather than a large upfront licence fee, which makes it financially viable for a new NBFC processing a few hundred loans a month as well as an established lender processing tens of thousands.












Sign in to leave a comment.