

India's Non-Banking Financial Companies (NBFCs) have become the backbone of personal credit delivery in the country, serving millions of borrowers who banks often overlook — gig workers, first-time borrowers, small business owners, and residents of tier-2 and tier-3 towns. But as personal loan books scale from hundreds to hundreds of thousands of accounts, spreadsheets, manual underwriting, and disconnected systems stop working. A single missed EMI reminder, a delayed credit bureau update, or a compliance gap in digital lending disclosures can cost an NBFC its reputation, its RBI standing, and its customers' trust.
This is where personal loan management software comes in. A modern Loan Management System (LMS) is no longer a "nice-to-have" back-office tool — it is the operating system of a lending business. It governs how fast you can disburse a loan, how accurately you calculate interest and penalties, how well you detect fraud and delinquency early, and how confidently you can walk into an RBI audit.
This guide walks through what personal loan management software actually does, the features that separate a genuinely useful platform from a glorified spreadsheet, how to evaluate vendors, what compliance obligations NBFCs must build into their tech stack, and how a platform like Roopya.money is purpose-built to solve these problems for banks and NBFCs operating in India's fast-moving digital lending market.
What Is Personal Loan Management Software?
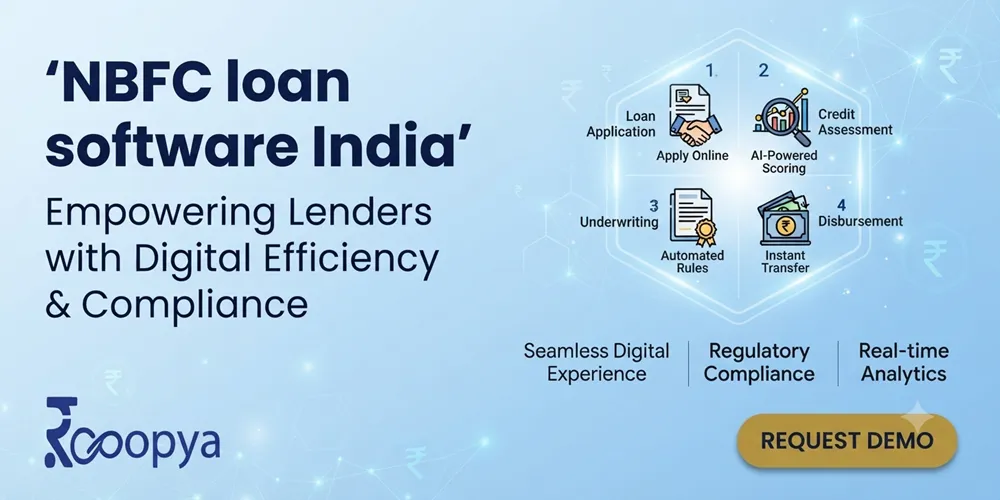
Personal loan management software is a digital platform that automates and manages the entire lifecycle of a personal loan — from the moment a borrower applies to the day the loan is fully repaid (or written off). Unlike a basic loan origination tool that only handles the application and approval stage, a complete LMS covers:
- Loan origination — application capture, KYC, credit checks, and approval workflows
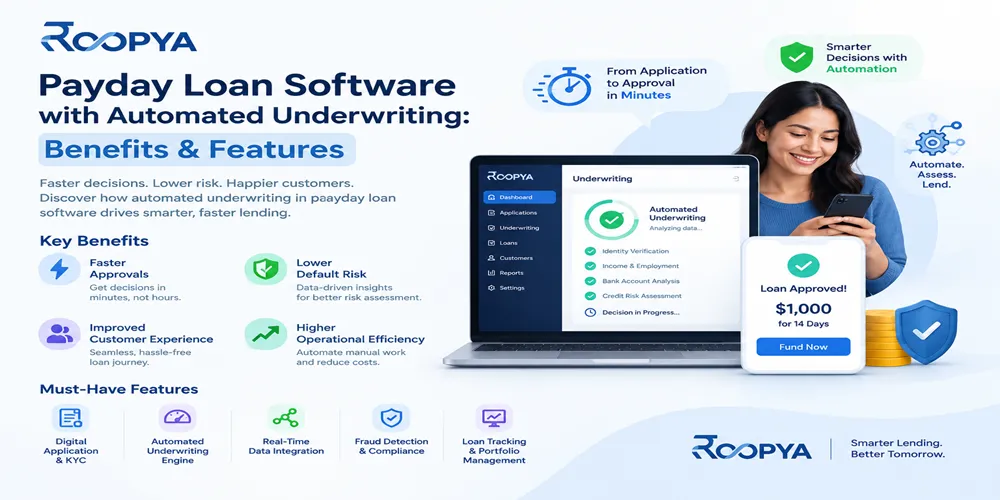
- Underwriting and credit decisioning — risk scoring, eligibility rules, and automated or assisted approvals
- Disbursement — fund transfer, agreement generation, and e-sign/e-mandate setup
- Servicing — EMI schedules, repayment tracking, ledger management, and customer communication
- Collections and recovery — delinquency buckets, reminders, field collection workflows, and legal escalation
- Accounting and reporting — NPA classification, provisioning, GST, and regulatory MIS reports
- Compliance — RBI digital lending guidelines, Key Fact Statements (KFS), data localization, and audit trails
In short, it is the single system of record that connects your sales team, credit team, collections team, finance team, and compliance team around one accurate, real-time view of every loan account.
Why NBFCs Specifically Need Purpose-Built Software
Banks have long had core banking systems; NBFCs historically grew faster than their technology. Many NBFCs — especially newer digital-first lenders — started with Excel-based tracking or generic CRM tools bolted together with manual processes. This works for the first few hundred loans. It breaks down almost immediately once:
- Loan volumes cross a few thousand active accounts
- Co-lending or Business Correspondent (BC) partnerships are introduced
- Multiple loan products (personal loans, instant loans, BNPL-style credit) run simultaneously
- RBI tightens reporting, disclosure, and outsourcing norms for digital lending
- Investors or rating agencies demand audit-ready, real-time portfolio data
A purpose-built personal loan management software, designed around NBFC and digital lending regulations from day one, removes this ceiling and lets a lending business scale without rebuilding its tech stack every 18 months.
Core Features of a Modern Loan Management System
Not all "LMS" platforms are built the same. When evaluating software — including Roopya.money — NBFCs should look closely at the following functional areas.
1. Digital Loan Origination and Onboarding
The borrower's first experience with your brand happens here, and it sets the tone for the entire relationship. Look for:
- Mobile- and web-based application forms with minimal fields and smart auto-fill
- Aadhaar-based e-KYC, PAN verification, and video KYC (V-CIP) support
- Integration with credit bureaus (CIBIL, Experian, Equifax, CRIF High Mark) for instant bureau pulls
- Bank statement analysis and income verification (via account aggregator or statement parsing)
- Configurable, multi-step application workflows that can be adjusted per product without needing a developer
2. Credit Underwriting and Rule-Based Decisioning
This is where risk is priced and bad loans are prevented before they happen. A strong LMS should offer:
- A rules engine to configure eligibility criteria (income multiples, bureau score cut-offs, FOIR/obligation ratios) without code
- Support for both automated straight-through processing (STP) for low-risk applicants and manual underwriter queues for edge cases
- Risk-based pricing — different interest rates or loan amounts based on the applicant's risk tier
- Fraud and identity checks (device fingerprinting, duplicate PAN/Aadhaar detection, blacklist checks)
- Full audit trail of every underwriting decision, with the rule or officer responsible for the outcome
3. Loan Disbursement and Documentation
Once approved, the system should handle:
- Auto-generation of loan agreements, sanction letters, and the mandatory Key Fact Statement (KFS) as required under RBI's digital lending framework
- E-stamping and e-signature integration
- E-NACH / UPI AutoPay mandate setup for EMI collection
- Direct disbursement to the borrower's bank account with reconciliation against the bank statement
4. Loan Servicing and EMI Management
This is the heart of day-to-day operations:
- Automatic EMI schedule generation (reducing balance or flat rate, as configured)
- Real-time loan ledger with interest accrual, principal outstanding, charges, and penalties
- Support for part-prepayments, foreclosures, and restructuring
- Auto-reconciliation of repayments received via NACH, UPI, or manual channels
- Customer self-service portal/app to view statements, download NOCs, and make payments
5. Collections and Delinquency Management
Collections is where many NBFCs lose the most money to inefficiency. Good software should provide:
- Automated bucket-wise classification (0-30, 31-60, 61-90+ DPD) that updates daily
- Configurable reminder workflows — SMS, WhatsApp, email, and IVR — triggered by days-past-due
- Field collection agent apps with geo-tagged visit logging and receipt generation
- Promise-to-pay (PTP) tracking and broken-PTP alerts
- Integration with legal recovery and SARFAESI/arbitration workflows where applicable
- Fair-practice compliant collection scripts and call recording/logging for RBI's recovery agent guidelines
6. NPA Classification, Accounting, and Finance
The software must speak the language of your finance and compliance teams:
- Automated NPA classification as per RBI's Income Recognition and Asset Classification (IRAC) norms
- Provisioning calculations aligned to Ind AS 109 (Expected Credit Loss model)
- GST-compliant invoicing for processing fees and charges
- General ledger integration or export to accounting systems (Tally, SAP, Oracle)
- Investor and lender MIS — portfolio-at-risk (PAR), vintage analysis, and cohort reporting for co-lenders or debt investors
7. Compliance and Regulatory Reporting
For an NBFC, this is non-negotiable. The platform should support:
- RBI's Digital Lending Guidelines — KFS disclosure, cooling-off period, no data sharing with unauthorised third parties, and Lending Service Provider (LSP) disclosure requirements
- Data localization and storage within India
- Grievance redressal workflows with defined turnaround times
- Credit Information Companies (CIC) reporting — monthly bureau data submission in the prescribed format
- RBI returns and statutory reporting formats (where applicable to the NBFC's category)
- Complete, exportable audit logs for every user action on a loan file
8. Analytics, Dashboards, and Reporting
Finally, leadership and risk teams need visibility without waiting for a monthly spreadsheet:
- Real-time dashboards for disbursement volume, portfolio quality, collection efficiency, and branch/agent performance
- Custom report builder for ad hoc analysis
- API access or data warehouse exports for teams that want to build their own BI layer
The Personal Loan Lifecycle, Stage by Stage
To understand why an integrated LMS matters, it helps to walk through what actually happens to a single personal loan application, end to end, and where things typically go wrong without the right software.
Stage 1: Lead capture and application. A borrower discovers your product through a website, app, partner, or Business Correspondent. Without a digital intake system, this stage alone can take days of back-and-forth over WhatsApp or phone calls to collect documents — a major source of drop-off. A good LMS captures the application once, digitally, and never asks the borrower for the same document twice.
Stage 2: KYC and verification. PAN, Aadhaar, address proof, and increasingly, video KYC, must all be verified against government and bureau databases. Manual verification introduces both delay and fraud risk — a staff member might miss a mismatched name or an expired document that an automated check would flag instantly.
Stage 3: Credit assessment. The system pulls a bureau report, checks income documents or bank statements, and applies your underwriting rules. This is where risk is genuinely priced. NBFCs without automated rules engines often rely on underwriters making judgment calls inconsistently across cases — which not only increases bad debt but also creates fair-lending and audit concerns.
Stage 4: Approval and offer. The borrower receives a loan offer with clearly disclosed terms — interest rate, processing fee, tenure, and all-in cost (APR). Under RBI's digital lending rules, this disclosure must take the form of a standardised Key Fact Statement, generated consistently for every loan, every time.
Stage 5: Agreement and disbursement. The borrower e-signs the agreement, sets up an e-mandate for EMI collection, and funds are disbursed — ideally within minutes for a well-automated digital lender, versus days for a manual process.
Stage 6: Servicing. For the life of the loan — often 12 to 60 months — the system must track every rupee: interest accrued, EMIs paid, charges levied, and the exact outstanding balance at any moment. Any drift here, even a rounding error compounded across thousands of accounts, becomes a reconciliation nightmare and a potential compliance issue.
Stage 7: Collections (when needed). The moment a payment is missed, the system should move the account into the appropriate bucket and trigger the right communication — gently at first, more structured as days-past-due increases — while keeping a complete, defensible record of every interaction for regulatory purposes.
Stage 8: Closure or write-off. Whether a loan is paid off in full, foreclosed early, or ultimately written off as a loss, the system needs to close the loop cleanly: issuing a No Objection Certificate (NOC), updating the bureau, and reflecting the final status in your books.
Every one of these eight stages involves different data, different stakeholders, and different regulatory obligations. When they live in one connected system, errors are caught early and reporting is accurate by default. When they live in five different tools — or in spreadsheets — errors compound silently until an audit, an investor review, or an unhappy customer forces them into the open.
Measurable Benefits of Adopting Loan Management Software
NBFC leadership teams considering the investment in a dedicated LMS typically see returns across four areas:
- Faster time-to-disbursement. Digitising origination and underwriting can cut the time from application to disbursal from days to minutes for straight-through-processed loans, directly improving conversion rates and borrower satisfaction.
- Lower operating cost per loan. Automating manual, repetitive tasks — document collection, EMI reminders, reconciliation — reduces the headcount needed to service a growing loan book, which matters enormously as volumes scale into the tens of thousands of accounts.
- Improved portfolio quality. Consistent, rules-based underwriting combined with early-stage collections automation reduces slippage into NPA categories, directly protecting the bottom line.
- Audit and fundraising readiness. NBFCs that can produce clean, real-time portfolio data are in a far stronger position when raising debt capital, negotiating co-lending partnerships, or facing an RBI inspection. Investors and rating agencies increasingly treat technology maturity as a proxy for operational discipline.
The Role of AI and Automation in Modern Loan Management
The next wave of personal loan management software is increasingly shaped by artificial intelligence and automation layered on top of the core LMS functions described above:
- AI-assisted underwriting that goes beyond static bureau scores to model repayment behaviour using alternate data — utility payments, transaction patterns, and device signals — particularly valuable for thin-file or new-to-credit borrowers that traditional scoring underserves.
- Predictive collections that flag accounts likely to default before they miss a payment, allowing proactive outreach rather than reactive recovery.
- Conversational AI for servicing — WhatsApp and chatbot-based self-service for EMI queries, statement requests, and basic grievance handling, reducing call-centre load.
- Document intelligence that reads and validates uploaded KYC documents, bank statements, and salary slips automatically, flagging inconsistencies for human review instead of requiring manual checking of every file.
NBFCs evaluating software today should ask not just what a platform automates now, but how actively the vendor is investing in these AI-driven capabilities, since they increasingly separate market leaders from legacy systems.
Implementation Roadmap: Going Live Without Disrupting Your Business
Switching to — or adopting your first — loan management system doesn't have to mean pausing operations. A well-run implementation typically follows four phases:
- Discovery and configuration (2-4 weeks). Map your existing loan products, interest calculation methods, approval workflows, and compliance requirements into the new system's configuration, without writing code.
- Integration (2-6 weeks, often run in parallel). Connect credit bureaus, payment and mandate rails, e-KYC providers, and accounting systems. This is the phase most likely to surface surprises, so insist on testing with live (not sandbox-only) data wherever possible.
- Pilot and parallel run (2-4 weeks). Run a subset of new originations through the new system while your legacy process continues for the remainder, comparing outputs — EMI schedules, NPA tagging, KFS generation — line by line for accuracy before full cutover.
- Full migration and go-live. Move all active loan accounts and historical data into the new system, retire legacy tools, and ramp training for sales, credit, collections, and finance teams who will use the platform daily.
A platform built for NBFCs — with templates for common loan products and compliance workflows already in place — compresses this timeline considerably compared to a system designed for generic lending use cases that then needs to be retrofitted for Indian regulatory requirements.
Build vs. Buy: Should Your NBFC Build Its Own LMS?
This is one of the most common strategic questions founders and CTOs of NBFCs face. Here's a balanced way to think about it:
Building in-house makes sense when:
- You have a dedicated, well-funded engineering team with lending-domain experience
- Your product is genuinely novel and no off-the-shelf system supports your use case
- You have 18-24 months of runway to invest before the system is production-ready
- Long-term platform ownership is a strategic differentiator for your business
Buying (or licensing) a purpose-built platform makes sense when:
- You want to get to market in weeks, not years
- Your team's strength is lending and credit, not software engineering
- You need built-in RBI compliance that's maintained and updated as regulations change
- You want predictable costs (subscription/transaction-based) instead of open-ended engineering spend
- You plan to scale loan volumes quickly and need infrastructure that's already battle-tested
For the overwhelming majority of NBFCs — particularly those focused on personal loans and digital-first lending — buying a configurable, compliance-ready platform like Roopya.money is the faster, lower-risk path. It lets the lending business focus its capital and talent on credit strategy, partnerships, and customer acquisition, while the software handles process automation and regulatory change management.
How to Evaluate Personal Loan Management Software: A Checklist
Use this checklist when shortlisting vendors:
- Does it cover the full loan lifecycle, from origination to closure, or only part of it (requiring you to stitch together multiple tools)?
- Is it configurable without code? Can your operations team change an interest calculation method, add a new loan product, or modify a workflow without raising a developer ticket?
- Is it built for Indian regulatory requirements — KFS generation, IRAC-based NPA classification, CIC reporting formats — out of the box?
- Does it integrate with your existing ecosystem — credit bureaus, payment gateways, NACH/UPI AutoPay, e-KYC providers, and accounting systems — via documented APIs?
- How does it handle scale? Can it comfortably support 10x your current loan volume without a re-platforming project?
- What is the implementation timeline? Weeks or months? Ask for reference NBFCs who went live recently.
- Is data hosted in India, with clear data ownership and exit-clause terms if you switch vendors later?
- What does pricing look like — per-loan transaction fee, flat SaaS fee, or a hybrid? Model this against your projected loan volumes for the next two years.
- What support and SLAs are offered post go-live, particularly for compliance-related issues that can't wait?
- Can it support co-lending and Business Correspondent (BC) structures if that's part of your growth strategy?
Common Mistakes NBFCs Make When Choosing Loan Management Software
- Choosing a generic CRM instead of a lending-specific system. CRMs track leads well but can't calculate accrued interest, classify NPAs, or generate a compliant KFS.
- Underestimating compliance requirements until an audit forces the issue. Retrofitting compliance into a live system is far more expensive than building on a compliant platform from day one.
- Ignoring collections workflows during vendor selection. Teams often optimize heavily for origination speed and treat collections as an afterthought — even though collections efficiency has the single biggest impact on NBFC profitability.
- Not stress-testing integrations. A platform that looks great in a demo can fail when connected to your actual bureau, payment gateway, and e-KYC vendors. Always run a pilot with live integrations before committing.
- Overlooking data portability. If you can't easily export your full loan book and transaction history, you're locked in — ask about this before signing a contract, not after.
How Roopya.money Helps NBFCs Manage the Personal Loan Lifecycle
Roopya.money is built specifically for the realities of Indian lending — banks and NBFCs that need to move fast, stay compliant, and scale their personal loan books without re-engineering their technology every time volumes grow or regulations change.
With Roopya.money, lending teams get:
- End-to-end lifecycle coverage — from digital application and e-KYC through underwriting, disbursement, servicing, collections, and closure — in a single connected platform, instead of stitching together point solutions.
- No-code configurability — business teams can launch new loan products, adjust interest and fee structures, or redesign approval workflows without waiting on engineering cycles.
- RBI-aligned compliance by design — automated KFS generation, IRAC-based NPA classification, audit trails, and reporting formats built around India's digital lending guidelines, so compliance isn't bolted on after the fact.
- Integration-ready architecture — pre-built connectors for leading credit bureaus, payment and mandate systems (NACH/UPI AutoPay), and e-KYC providers, so go-live doesn't depend on months of custom integration work.
- Collections intelligence — automated bucket classification, multi-channel reminder workflows, and field-agent tools designed to reduce delinquency before it becomes NPA.
- Real-time portfolio visibility — dashboards built for credit, finance, and leadership teams to track disbursement, portfolio quality, and collection performance without waiting for a monthly report.
Whether you're an NBFC launching your first digital personal loan product or an established lender outgrowing a legacy system, Roopya.money is designed to be the operational backbone that lets you focus on growing a healthy loan book — not firefighting process and compliance gaps.
Key Takeaways
- Personal loan management software is the system of record for the entire loan lifecycle — origination, underwriting, disbursement, servicing, collections, and compliance reporting — not just a front-end application form.
- NBFCs outgrow spreadsheets and generic CRMs quickly once volumes, products, or partnership structures (such as co-lending) grow in complexity.
- Compliance with RBI's digital lending guidelines, including Key Fact Statement disclosure and IRAC-based NPA classification, should be built into the platform from day one rather than retrofitted later.
- Collections capability is as important as origination speed when evaluating software — it has an outsized impact on portfolio quality and profitability.
- For most NBFCs, licensing a purpose-built, configurable platform like Roopya.money is faster, lower-risk, and more cost-effective than building an in-house LMS from scratch.
Conclusion
Personal loan management software has moved from a back-office convenience to a strategic necessity for NBFCs operating in India's increasingly regulated, increasingly digital lending market. The right platform does more than automate paperwork — it protects asset quality through better underwriting and collections discipline, keeps you audit-ready for RBI, and gives your leadership team the real-time visibility needed to make confident decisions.
As you evaluate options, weigh the full loan lifecycle, compliance readiness, integration depth, and collections capability — not just how fast a demo can originate a loan. Platforms like Roopya.money are built to meet NBFCs where they are today and scale with them as loan books, products, and regulatory requirements grow.
If you're ready to see how a purpose-built loan management system can streamline your personal loan operations, visit [roopya.money](https://roopya.money/) to learn more or request a walkthrough.
Frequently Asked Questions
1. What is personal loan management software?
Personal loan management software is a digital platform that automates the complete lifecycle of a personal loan — application, KYC, credit underwriting, disbursement, EMI servicing, collections, NPA classification, and regulatory reporting — within a single connected system.
2. Why do NBFCs need a dedicated loan management system instead of a spreadsheet or CRM?
Spreadsheets and generic CRMs cannot calculate accrued interest accurately, classify NPAs as per RBI's IRAC norms, generate a compliant Key Fact Statement, or scale safely beyond a few hundred accounts. A dedicated LMS is purpose-built for these lending-specific calculations and compliance requirements.
3. Is loan management software mandatory for NBFCs under RBI regulations?
RBI does not mandate a specific software vendor, but it does mandate the outcomes a proper LMS delivers — such as standardised Key Fact Statements for digital loans, accurate NPA classification, auditable records, and timely credit bureau reporting. In practice, meeting these obligations reliably at scale requires dedicated software.
4. How long does it take to implement a loan management system?
A well-configured, purpose-built platform for NBFCs can typically go live in 6-12 weeks, covering discovery, configuration, integration with bureaus and payment rails, a parallel pilot run, and full migration. Generic or heavily customised systems often take considerably longer.
5. Can loan management software handle co-lending and Business Correspondent (BC) models?
Yes — platforms designed for the Indian lending market, including Roopya.money, support co-lending structures and BC partnerships with configurable workflows, partner-wise reporting, and reconciliation built in.
6. What is a Key Fact Statement (KFS) and why does it matter?
A Key Fact Statement is a standardised disclosure document, mandated under RBI's digital lending guidelines, that clearly states a loan's interest rate, fees, annual percentage rate (APR), and other key terms before the borrower accepts the loan. A compliant LMS generates this automatically for every digital loan.
7. How does loan management software improve collections?
It automates delinquency-bucket classification, triggers timely multi-channel reminders (SMS, WhatsApp, email, IVR), tracks promise-to-pay commitments, and gives field agents mobile tools for structured, auditable recovery — reducing the share of loans that slip into serious delinquency.
8. Is my loan data secure and compliant with Indian data localization rules on platforms like Roopya.money?
Yes. Platforms built for Indian banks and NBFCs host data within India and are designed around the data protection and localization expectations that apply to regulated financial institutions.
9. What does personal loan management software typically cost?
Pricing models vary — common structures include a per-loan transaction fee, a flat monthly SaaS subscription, or a hybrid of the two. Costs should be evaluated against projected loan volumes over the next 12-24 months rather than current volumes alone.
10. How is Roopya.money different from generic loan software?
Roopya.money is built specifically for Indian banks and NBFCs, with RBI-aligned compliance (KFS generation, IRAC-based NPA classification, audit trails), no-code configurability for new products and workflows, and pre-built integrations with credit bureaus, payment/mandate rails, and e-KYC providers — covering the full loan lifecycle in one connected platform.














Sign in to leave a comment.