

Starting a medical practice is an exciting step for any healthcare professional. It is also a major business decision that requires careful financial planning. From securing a suitable location and purchasing medical equipment to hiring staff and covering early operating expenses, a new practice can require significant capital before it begins generating consistent revenue.
For many healthcare professionals, using personal savings alone may not be enough to cover these costs. This is where SBA loans for medical startups can become an important financing option. SBA backed financing may help eligible healthcare entrepreneurs access capital for qualified business expenses while giving them a structured way to manage repayment.
Understanding how SBA financing works, what it can potentially be used for, and what lenders may consider can help medical professionals make more informed decisions when planning a new practice.
Why Medical Startups Need Access to Capital
Launching a medical practice involves more than purchasing a few pieces of equipment and opening the doors. There are many expenses that need to be handled before the practice has a steady stream of patients.
A new practice may need to pay for leasehold improvements, office furniture, medical equipment, technology, software, insurance, licensing-related expenses, marketing, staffing, supplies, and professional services. There may also be several months of operating expenses before the business reaches its expected revenue level.
This early period can put pressure on a healthcare professional's personal finances if there is not enough business capital available.
Financing can provide the funds needed to establish the practice properly while preserving some personal savings for emergencies and unexpected expenses. The key is choosing a financing structure that matches the startup's needs and realistic ability to repay.
What Are SBA Loans for Medical Startups?
SBA loans are business financing options provided by participating lenders with support from the U.S. Small Business Administration. The SBA generally does not lend the money directly in most cases. Instead, approved lenders provide financing under SBA program guidelines, with the SBA providing a guarantee to the lender on a portion of an eligible loan.
For medical startups, SBA financing may be worth exploring when the business meets applicable eligibility requirements and the requested funds will be used for an eligible business purpose.
The SBA 7(a) program is particularly relevant to many small businesses because it can support several common business needs. Depending on the transaction and applicable rules, financing may potentially be used for working capital, equipment, real estate, business improvements, and qualifying business acquisitions.
Because each application is different, medical professionals should review the current program requirements and discuss their specific situation with an experienced lender.
How SBA Financing Can Help Start a Medical Practice
One of the biggest advantages of financing is that it can allow a healthcare professional to establish a practice without having to fund every expense from personal savings.
For example, a physician may have a strong business plan but need capital to renovate an office, purchase equipment, hire employees, and cover initial operating expenses. Financing can help bring these pieces together so the practice is ready to serve patients from the beginning.
The funding can also help a new practice create a professional environment that supports efficient operations. SBA medical financing can help eligible healthcare professionals invest in appropriate technology, comfortable patient areas, reliable equipment, and effective administrative systems, making a difference in how smoothly the business operates.
However, financing should be based on a realistic startup budget. Borrowing more than the practice can reasonably support may create unnecessary financial pressure during the early stages of the business.
SBA 7(a) Financing for Medical Startups
The SBA 7(a) loan program is one of the most widely used SBA financing programs for small businesses. For eligible medical startups, it may offer flexibility because financing can potentially support multiple business purposes within program guidelines.
A startup may have several expenses that need to be covered at the same time. Rather than financing only one piece of the project, an eligible SBA 7(a) structure may potentially address several qualified costs within one financing plan.
The amount available, repayment terms, interest rate, collateral considerations, equity requirements, and other conditions depend on the lender, the transaction, and SBA requirements.
Medical professionals should not assume that simply being a healthcare provider guarantees approval. The lender will still evaluate the overall strength and feasibility of the business.
What Can SBA Financing Be Used For?
The exact permitted use of funds depends on the SBA program and the specific loan structure. For an eligible medical startup, financing may potentially support qualified expenses such as working capital, equipment, furniture, technology, renovations, and certain real estate-related costs.
Working capital can be particularly important during the early months of a practice. Revenue may take time to become consistent, while expenses such as payroll, rent, utilities, supplies, insurance, and administrative costs begin immediately.
Having adequate working capital can help the practice operate normally while building its patient base.
Financing Medical Equipment
Medical equipment can represent a substantial portion of the startup budget. Depending on the specialty, a new practice may need diagnostic systems, treatment equipment, computers, imaging technology, laboratory equipment, or other specialized tools.
The right equipment can help a practice provide better services and operate more efficiently.
However, purchasing everything upfront can consume a large amount of available cash.
Eligible SBA financing may potentially help cover qualified equipment expenses. Another option may be specialized medical equipment financing, depending on the practice's circumstances and the lender's available programs.
The best approach depends on the equipment being purchased, its cost, the expected useful life, and the practice's overall financial plan.
Covering Startup Working Capital
Working capital is one of the most important financial considerations for a new medical practice.
A practice can have a well-designed office and excellent equipment but still struggle if it does not have enough cash to cover everyday expenses during the early months.
Startup working capital may help cover expenses such as employee wages, rent, supplies, technology, marketing, utilities, and other normal business costs.
Having a reasonable working capital cushion can give a new practice more time to build its patient base and establish predictable revenue.
SBA Loans and Medical Office Real Estate
For some healthcare professionals, purchasing a medical office building may make more sense than leasing a space. Owning the property can provide greater control over the location and may create a long term business asset.
Eligible SBA financing may potentially be used for certain owner-occupied commercial real estate projects. The specific requirements can vary, and the property generally needs to meet applicable SBA and lender guidelines.
Medical professionals considering real estate should look beyond the purchase price. They should also consider renovations, closing costs, property taxes, insurance, maintenance, utilities, and other ongoing expenses.
A well-planned real estate investment can support the long-term growth of a medical practice, but it should fit comfortably within the overall business strategy.
What Lenders Look for in Medical Startup Applications
Obtaining startup financing can be more challenging than financing an established business because a new practice does not have years of business revenue to demonstrate its performance.
As a result, lenders may place significant importance on the owner's professional background, credit history, business plan, financial projections, available capital, industry experience, and overall ability to manage the business.
A strong business plan can make a meaningful difference. It should clearly explain the services the practice will provide, the target patient market, expected expenses, pricing or reimbursement assumptions, competition, staffing plans, and projected revenue.
For healthcare professionals, clinical experience is valuable, but running a medical practice also requires business management. Demonstrating an understanding of both sides can strengthen the overall financing presentation.
The Importance of a Strong Business Plan
A business plan is more than a document created for a lender. It can serve as a roadmap for the practice owner.
Before applying for financing, a healthcare professional should have a clear idea of how much money is actually needed and how the funds will be used.
For example, if the total startup cost is estimated at $750,000, the owner should understand how much will go toward equipment, renovations, technology, working capital, professional expenses, and other startup costs.
Financial projections should also be realistic. It is easy to assume that a new practice will quickly attract a large number of patients, but actual patient growth can take time.
A conservative financial forecast can help the owner prepare for slower-than-expected revenue during the first few months.
Can New Medical Practices Qualify Without a Long Business History?
This is one of the most common concerns among healthcare professionals preparing to launch a practice.
A new practice does not have an established business history, but that does not automatically mean financing is impossible. Eligibility depends on the specific SBA program, lender requirements, the owner's financial profile, the business plan, projected cash flow, equity contribution, and other factors.
A healthcare professional with strong industry experience and a well-prepared business plan may present a different risk profile from someone with little professional or business experience.
Because requirements can vary, it is important to discuss the startup structure with a lender before assuming that a particular financing option will or will not work.
Preparing for the SBA Loan Application
Preparation can make the financing process easier.
A medical professional should organize personal and business financial information, develop a detailed startup budget, prepare realistic financial projections, and clearly explain how the requested funds will be used.
It is also helpful to understand personal credit history and existing financial obligations before beginning the application process.
The more clearly the lender can understand the business model and financing request, the easier it may be to evaluate the application.
A strong application does not guarantee approval, but good preparation can help avoid unnecessary delays caused by missing or unclear information.
How Much Should a Medical Startup Borrow?
There is no universal loan amount that is right for every medical startup.
The appropriate amount depends on the size of the practice, specialty, location, equipment requirements, staffing plans, real estate costs, expected patient volume, and available personal or business capital.
The goal should be to borrow enough to establish and operate the practice properly without taking on more debt than the business can reasonably support.
Underestimating startup expenses can be just as problematic as borrowing too much. If the practice runs out of working capital shortly after opening, the owner may need to seek additional financing under less favorable circumstances.
That is why a detailed startup budget is so important.
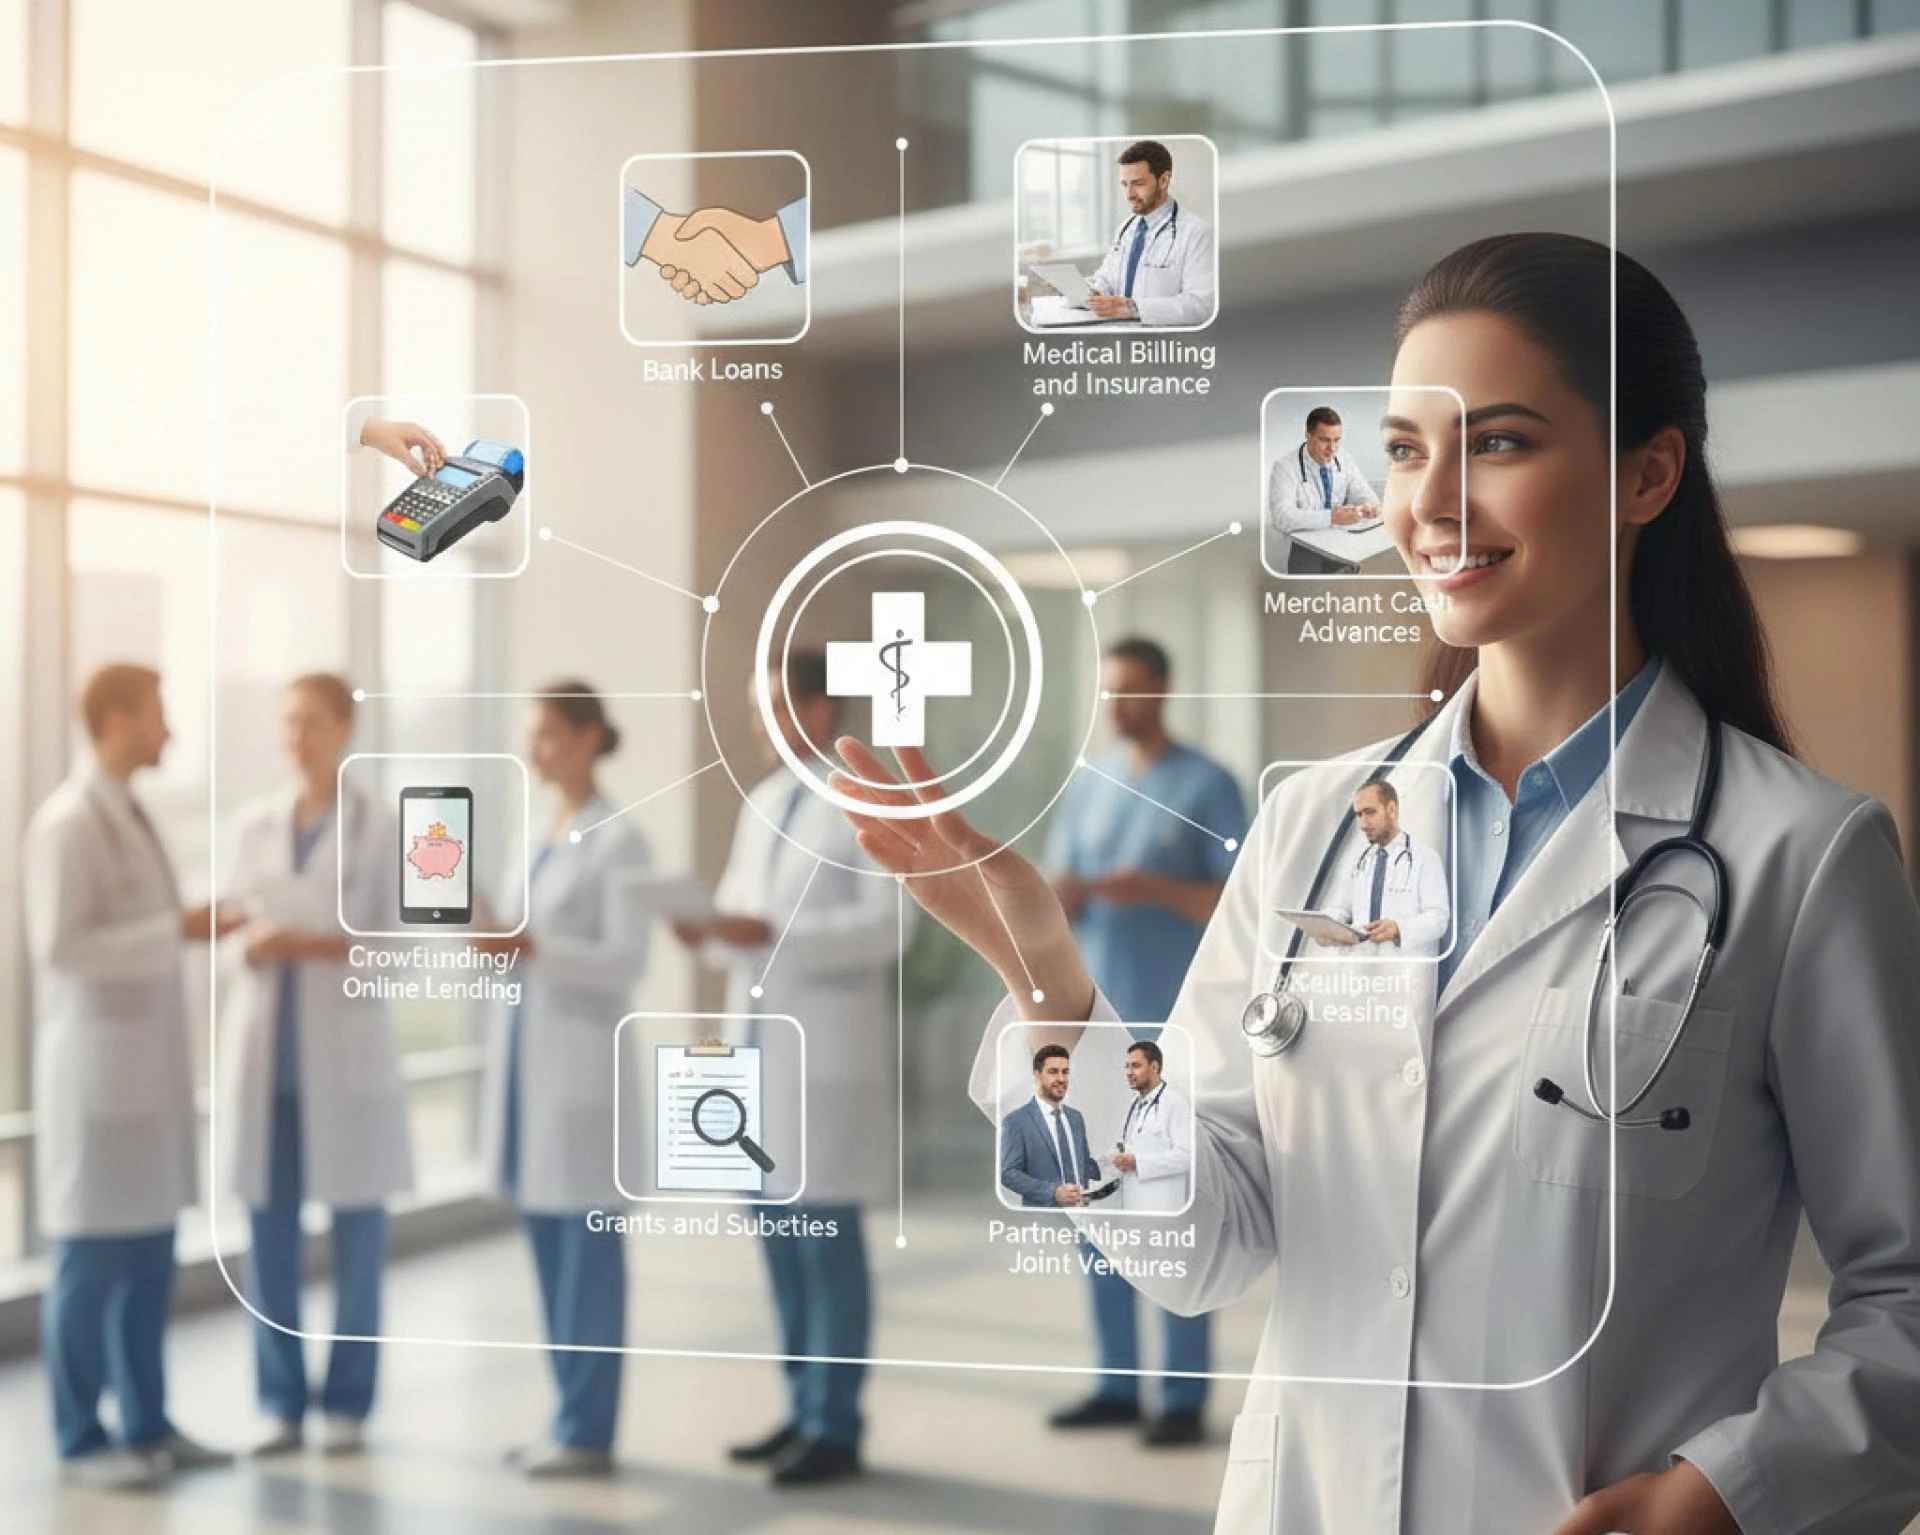
SBA Financing vs. Other Medical Practice Financing
SBA financing is not the only option available to healthcare professionals.
Depending on the need, a practice owner may also consider conventional business loans, medical equipment financing, healthcare working capital financing, term loans, healthcare real estate financing, or other specialized funding solutions.
Each option has its own advantages and requirements.
For example, equipment financing may be more appropriate when the primary need is purchasing medical technology. A working capital solution may make more sense when the practice needs short-term liquidity. Real estate financing may be better suited for purchasing an owner-occupied medical facility.
The best financing solution depends on the specific goal rather than simply choosing the loan with the largest available amount.
Common Mistakes to Avoid
One common mistake is creating a startup budget that focuses only on the initial purchase costs. Medical professionals sometimes calculate the cost of equipment, furniture, and renovations but forget about ongoing expenses during the first few months.
Another mistake is assuming that projected revenue will begin immediately. A new practice may take time to build a patient base and establish reliable collections.
It is also important not to overlook the total cost of financing. Interest, fees, repayment terms, collateral requirements, and other conditions should all be reviewed before accepting an offer.
Most importantly, financing should support a practical business plan. The loan itself should not become the business plan.
Why Healthcare-Focused Financing Matters
Healthcare businesses have unique financial characteristics. Medical billing cycles, insurance reimbursements, equipment costs, staffing requirements, and regulatory considerations can all influence the financial performance of a practice.
Working with a financing provider that understands healthcare can make the conversation more relevant to the actual needs of the business.
National Medical Funding specializes in financing solutions for healthcare professionals and medical practices. The company helps medical professionals explore funding options for working capital, equipment, practice expansion, real estate, acquisitions, and other qualified business needs.
For a medical startup, having access to a knowledgeable financing partner can be valuable when evaluating different ways to fund the business.
Building a Strong Financial Foundation for Your Medical Startup
Opening a medical practice requires careful planning, patience, and a realistic understanding of the costs involved.
SBA financing can be an option for eligible medical entrepreneurs who need capital to establish and grow their businesses. Whether the funds are needed for equipment, working capital, renovations, technology, real estate, or other qualified expenses, the right financing structure can help a healthcare professional move forward with greater financial confidence.
The most important step is to understand the practice's actual needs before choosing a financing option. A thoughtful business plan, realistic projections, appropriate capital structure, and clear repayment strategy can create a stronger foundation for long-term success.
A medical practice is both a healthcare operation and a business. Giving equal attention to patient care and financial planning can help create a practice that is prepared not only to open its doors but also to grow over time.
Frequently Asked Questions About SBA Loans for Medical Startups
Can a medical startup get an SBA loan?
A medical startup may qualify for certain SBA financing programs if it meets the applicable SBA and lender requirements. Approval can depend on factors such as the owner's credit profile, professional experience, business plan, projected cash flow, equity contribution, and the intended use of funds.
What can SBA financing be used for when starting a medical practice?
Depending on the SBA program and lender requirements, financing may potentially be used for qualified expenses such as working capital, equipment, furniture, renovations, technology, and certain owner-occupied commercial real estate costs.
Is an SBA 7(a) loan suitable for a medical startup?
SBA 7(a) financing can be worth considering because of its flexibility for eligible small businesses. It may potentially support several qualified business purposes, but whether it is appropriate depends on the startup's needs, financial profile, eligibility, and lender requirements.
How much money can a medical startup borrow?
The amount a medical startup can qualify for depends on the financing program, lender, project costs, financial projections, credit profile, equity contribution, and ability to repay. There is no single loan amount that applies to every medical startup.
Do I need excellent credit to qualify for SBA financing?
Credit requirements vary by lender and loan program. Credit history is an important consideration, but lenders may also evaluate the business plan, professional experience, projected cash flow, available capital, and other financial factors.
Can SBA financing cover medical equipment?
Eligible SBA financing may potentially be used for qualified equipment purchases. Medical professionals should confirm the specific equipment and financing structure with their lender before proceeding.
Can I use SBA financing for working capital?
Yes, certain SBA financing programs may allow qualified businesses to use funds for working capital. This can be particularly helpful for a medical startup that needs cash to cover operating expenses while building its patient base.
Can SBA financing be used to purchase a medical office?
Certain SBA financing programs may potentially be used for eligible owner-occupied commercial real estate. The property and transaction must satisfy applicable SBA and lender requirements.
How long does it take to get an SBA loan?
The timeline varies based on the lender, loan size, complexity of the transaction, documentation, underwriting, and SBA processing requirements. A straightforward request may move more quickly than a large startup or real estate transaction.
Should I consider other financing options besides an SBA loan?
Yes. SBA financing may be a good option for some medical startups, but it is not the only choice. Equipment financing, working capital loans, term loans, real estate financing, and other healthcare-focused financing options may be appropriate depending on the specific need.
Final Thoughts
Starting a medical practice is a major investment in your professional future. Having the right financing in place can make it easier to purchase essential equipment, prepare your facility, hire the right team, manage early operating expenses, and build a strong foundation for growth.
SBA loans for medical startups may provide an opportunity for eligible healthcare professionals to access capital for qualified business purposes. However, choosing financing should always begin with a clear understanding of the practice's financial needs and long-term goals.












Sign in to leave a comment.