
A quiet queue tells the whole story
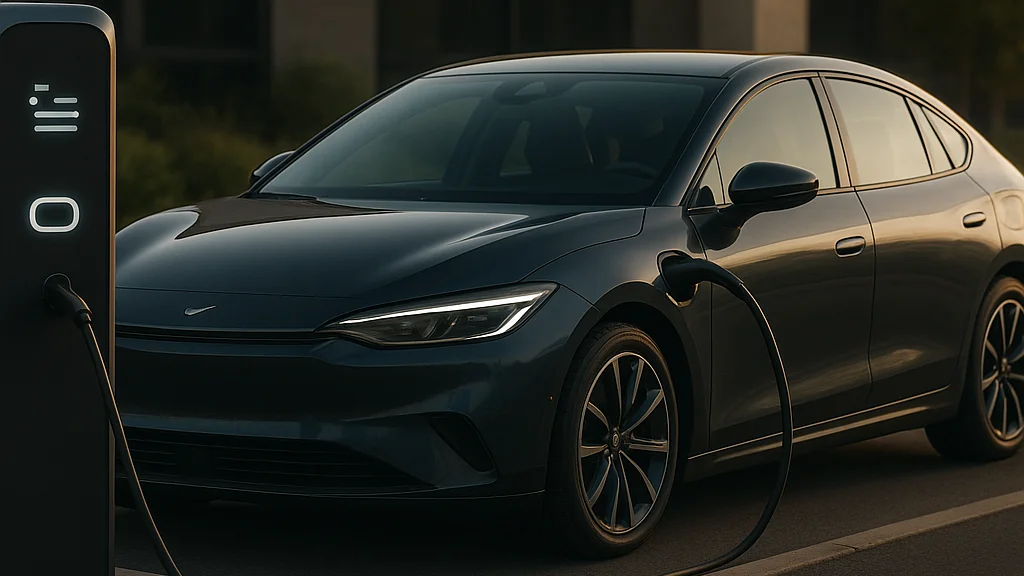
On a long highway outside a major city, the future of transport can look surprisingly ordinary: a row of drivers checking charge levels, a delivery van topping up between routes, a rideshare operator doing quick mental math about dwell time and earnings. The scene matters because electric vehicle adoption is no longer being held back mainly by vehicle choice. More often, the bottleneck is whether charging is available where people actually live, work, shop, and travel.
That shift is one of the defining green-tech stories of the decade. A few years ago, the public conversation focused on whether consumers would buy battery-electric cars at all. By 2026, the harder and more practical question is whether grids, property owners, charging operators, fleet depots, utilities, and regulators can build fast enough to support a larger electric fleet without creating new friction. Growth is happening, but it is uneven. Dense urban corridors are getting more attention than rural routes. Premium charging hubs are arriving faster than apartment retrofits. Passenger vehicles have led the market, yet buses, trucks, and delivery fleets are now forcing a deeper rethink of power demand and site design.
Industry forecasts underline the scale of the transition. According to Yahoo Finance reporting on a market forecast, the broader electric vehicle market is expected to expand at a 7.73% compound annual growth rate through 2034, reaching a headline figure of US$1.72 trillion. Forecasts should always be read with some caution, but the direction is clear: more EVs on the road require many more reliable charging points, higher-capacity connections, and smarter software to manage demand.
If there is a comforting truth here, it is this: infrastructure problems are difficult, but they are solvable. They respond to planning, standards, capital, and patience. For readers looking for a broad primer, this WriteUpCafe explainer and this analysis of how charging networks are scaling frame the same core issue from slightly different angles. The big picture is no longer hypothetical. Charging infrastructure growth is becoming one of the main ways countries either accelerate decarbonization or quietly slow it down.
The EV transition is not just about selling cleaner vehicles. It is about building a dependable energy-and-mobility system around them.
How we got here: from range anxiety to infrastructure anxiety
The first phase of the EV era was dominated by range anxiety. Buyers worried that batteries were too small, public chargers too rare, and charging times too long. Automakers responded by pushing larger packs, better thermal management, and more efficient drivetrains. Governments offered purchase incentives. Early adopters tolerated inconvenience because they were motivated by climate concerns, lower running costs, or simple curiosity.
Then the market matured. Battery ranges improved enough for many daily driving patterns. Home charging proved to be a powerful advantage for detached-house owners. Workplace charging expanded in pockets. Fast-charging standards became more common, and software for locating stations improved. As that happened, the anxiety moved. It became less about whether an EV could theoretically complete a trip and more about whether the charging ecosystem would be reliable at scale.
This distinction matters. A transport system can survive a low charger count when EV penetration is modest. It struggles when adoption rises quickly in places where permitting is slow, grid upgrades lag, or charger maintenance is poor. The problem is especially acute in multi-unit housing, where residents may not control parking spaces or electrical upgrades. It is also visible in logistics, where every minute of charging downtime can ripple through route planning and labor costs.
Governments and private operators have learned that charging deployment is not a single market. It is several. Home charging, destination charging, workplace charging, highway fast charging, depot charging, and heavy-duty corridor charging all have different economics. A suburban homeowner plugging in overnight is participating in a very different energy system than a freight operator seeking megawatt-scale throughput between distribution nodes.
That is why infrastructure growth now looks less like one clean trend line and more like a patchwork of local breakthroughs and local bottlenecks. Some regions have enough chargers on paper but not enough uptime. Others have good hardware supply but weak utility coordination. Some have public subsidies but poor site host incentives. The practical lesson is gentle but firm: charger counts alone are an incomplete measure of progress.
- Phase one: prove EV demand exists.
- Phase two: expand public and private charging access.
- Phase three: integrate charging with grid capacity, software, pricing, and fleet operations.
By 2026, many markets are somewhere between phases two and three. That is where the work gets more technical, and honestly, more interesting.
The numbers behind growth are impressive, but reliability is the real metric
Headlines often celebrate charger installation totals, and those totals do matter. They signal investment, policy momentum, and consumer confidence. Yet the more revealing metrics are utilization rates, uptime, charging speed consistency, and the ratio between EV growth and charger deployment. A station that exists but routinely fails, delivers slower-than-advertised speeds, or sits in the wrong location does less for the transition than a smaller network built around actual travel behavior.
Recent reporting from Australia offers a useful example. According to Canberra Daily, the country’s rise in electric-car adoption has put visible strain on parts of the charging network. That dynamic is not unique to Australia. It reflects a broader pattern seen in many growing EV markets: vehicle sales can accelerate faster than infrastructure planning cycles. When that happens, queues lengthen, user trust erodes, and critics gain an easy talking point.
For operators, this creates a delicate balancing act. Build too early, and assets may sit underused while financing costs bite. Build too late, and congestion damages brand reputation while regulators and drivers complain. The most sophisticated players are moving beyond simple site expansion toward load forecasting, battery-buffered charging, dynamic pricing, and partnerships with retailers, landlords, and utilities.
Heavy-duty transport raises the stakes further. A passenger EV fast charger is significant; a truck charging hub can be transformational for local power planning. Electric trucks, buses, and commercial fleets need high-power charging windows that align with operational schedules, not just consumer convenience. That is why the debut of products such as the BYD ETT 44 electric truck with 1.5 MW charging highlighted by Electric Cars Report matters beyond the vehicle itself. Megawatt-class charging changes the conversation from parking-lot amenity to industrial energy infrastructure.
Market optimism is also visible in sector forecasts. Mena FN’s coverage of the heavy-duty EV charging infrastructure market points to expected long-term expansion in this segment through 2034. Forecast articles are not the same as audited market results, but they capture a serious investment thesis: freight electrification will require a much denser and more powerful charging backbone than the passenger-car market alone.
The best charging network is not the one with the most pins on a map. It is the one drivers trust on a cold morning, a holiday weekend, and a tight delivery schedule.
- Availability: Is a charger actually open when drivers need it?
- Uptime: Does the hardware work consistently?
- Power delivery: Does charging speed match expectations?
- Location quality: Is the site where traffic naturally flows?
- Grid readiness: Can the local system support current and future demand?
Those five factors now define whether infrastructure growth is merely visible or genuinely useful.
What changed recently in 2026
The story in 2026 is less about novelty and more about specialization. Charging networks are becoming more segmented by use case, and that is a sign of maturity. Instead of assuming one solution can serve everyone, operators are designing around different behaviors: overnight residential charging, en-route ultra-fast charging, urban curbside access, depot charging for delivery fleets, and high-capacity corridor charging for trucks.
Commercial fleets are especially important this year because they can justify infrastructure investment with clearer economics than many private consumers. A fleet manager can model fuel savings, maintenance reductions, route patterns, and charger utilization with more precision than a household can. That is one reason corporate charging buildouts have accelerated. In India, for example, ETBrandEquity reported on Amazon using its own charging infrastructure to expand its electric delivery fleet. The significance goes beyond one company. Private charging ecosystems are becoming a parallel engine of infrastructure growth, particularly where public networks remain patchy.
Another notable development is the growing seriousness around heavy-duty charging standards and hardware. The truck segment used to feel like a future chapter. In 2026, it is arriving in real equipment, pilot corridors, and procurement strategies. That changes land-use planning, utility interconnection timelines, transformer demand, and the role of on-site storage. A truck stop retrofitted for megawatt charging is not simply a bigger version of a car charging plaza; it is a different category of energy node.
Meanwhile, policymakers in many regions are shifting from headline subsidy announcements toward more technical interventions: streamlined permitting, building-code updates, interoperability requirements, reliability standards, and grid modernization support. Those measures are less glamorous than ribbon-cutting photos, but they often matter more. A charger installed in six months instead of eighteen can alter local adoption patterns in a very real way.
Writers covering this beat have also become more candid about what success requires. The conversation has matured from “How many chargers?” to “Which chargers, where, for whom, and connected to what power?” For readers who want another angle on the current phase, this WriteUpCafe piece on charging infrastructure trends and insights and this article on progress and prospects help map the field.
There is a quiet comfort in that complexity. It means the sector is moving past slogans and into engineering, operations, and lived experience.
The hardest gaps are not on highways but in homes, depots, and local grids
Public fast chargers get the headlines because they are visible, expensive, and politically useful. Yet some of the most consequential infrastructure gaps are less photogenic. Apartment dwellers need dependable overnight access. Employers need enough capacity to support staff charging without blowing out building loads. Fleet depots need power upgrades that can take years to arrange. Utilities need to anticipate demand clusters before they become emergencies.
For many households, the fairest EV transition depends on solving charging access outside detached homes. If the easiest EV ownership model is still “have a driveway and install a charger,” then adoption will skew toward higher-income households and certain suburban geographies. Curbside charging, shared residential charging, and building retrofits are therefore not side issues. They are central to equity and market scale.
Depot charging presents another challenge. Delivery vans, municipal fleets, transit buses, and service vehicles often return to base on predictable schedules, which sounds ideal. In practice, those depots may need substantial electrical upgrades, smart charging software, and backup plans for operational peaks. A single fleet electrification project can require coordination among landlords, utilities, charger manufacturers, software vendors, and local authorities. Delays in any one of those relationships can stall the whole effort.
Grid integration is where the conversation becomes especially technical. Fast chargers create concentrated demand. Clusters of them create planning questions about transformers, substations, and local resilience. The answer is not to slow electrification; it is to pair charging growth with smarter energy management. That can include time-of-use pricing, managed charging, vehicle-to-grid experimentation in some markets, and co-located battery storage to smooth peaks.
- Apartment retrofits often face split incentives between landlords and tenants.
- Depot projects can be delayed by utility interconnection timelines.
- Rural corridors may struggle with lower utilization and weaker business cases.
- Urban fast-charging hubs can face land constraints and high real-estate costs.
- Grid upgrades frequently move slower than vehicle adoption curves.
These are not reasons for pessimism. They are reminders that infrastructure growth is really several construction and coordination stories happening at once.
Who is building the network, and who stands to benefit
The charging buildout is being shaped by a broad coalition, and each participant has different incentives. Utilities want manageable load growth and grid stability. Automakers want confidence that charging friction will not hurt sales. Oil majors and convenience retailers see a chance to reinvent roadside energy retail. Real-estate owners want amenities that improve occupancy and asset value. Fleet operators want lower total cost of ownership and route certainty. Governments want emissions reductions, industrial development, and voter-visible progress.
That mix can be messy, but it is also why the market is moving. No single actor has to carry the entire burden. The most effective projects often come from partnerships that align economics with public goals. A retail host may provide land, a charging company may finance and operate hardware, a utility may support interconnection planning, and a public agency may reduce permitting friction or offer targeted incentives.
There are also important differences between public and private returns. A highway charging hub may have strategic value beyond immediate profit because it expands the practical geography of EV ownership. A workplace charger may improve employee retention or sustainability reporting more than direct revenue. A depot charger may unlock measurable savings in fuel and maintenance while helping a company meet procurement or emissions targets.
For investors and policymakers, one of the most useful distinctions is between charger deployment and charger ecosystem quality. Hardware sales alone do not guarantee a durable market. Software, maintenance, payments integration, customer support, and grid services are increasingly where value is created or lost. The sector is maturing into an operational business, not just a hardware rollout.
That maturity is healthy. It means the conversation is finally catching up to the reality drivers already know: charging is not a symbol. It is a service. If it works well, people barely think about it. If it fails, they think about little else.
What to watch next: standards, speed, and the politics of patience
Over the next few years, three themes deserve close attention. First is standardization. Interoperability across vehicles, chargers, payment systems, and software platforms remains essential. Consumers do not want a maze of apps and inconsistent experiences. Fleet operators want predictable charging across regions and vendors. The more seamless the system becomes, the less psychological friction remains around EV ownership.
Second is speed, though not only charging speed. Deployment speed may matter more. A technically excellent charger that takes two years to permit and energize is less useful than a very good charger delivered in six months. Regions that simplify approvals, coordinate utility planning, and create predictable rules will almost certainly attract more private capital.
Third is the politics of patience. Infrastructure transitions rarely move in straight lines. There will be utilization mismatches, broken chargers, local opposition, and periods when vehicle sales outpace charging growth or vice versa. That should be expected. The more serious question is whether institutions keep refining the system instead of declaring the whole project flawed at the first visible strain.
One practical way to think about the next phase is to watch where charging becomes invisible. Success looks like routine. It looks like a tenant finding overnight charging at her building without a fight. It looks like a delivery fleet charging between shifts without operational drama. It looks like a family taking a road trip and remembering the scenery more than the charger map. When infrastructure fades into the background, adoption can move from early commitment to ordinary habit.
There is still a lot to build. Yet the momentum is real, the capital is real, and the need is real. EV charging infrastructure growth is no longer a supporting subplot in the clean transport story. It is the story that will determine how quickly electrification becomes practical for everyone, not just the easiest customers to serve.
If you are watching this space as a consumer, investor, policymaker, or simply a thoughtful neighbour, keep your eye on reliability, access, and grid readiness. Those are the quiet foundations under all the brighter promises. And if the pace feels uneven, take heart. Most meaningful transitions do. Be gentle with the future while it is under construction.












Sign in to leave a comment.